Owner’s earnings, not hype
We want a record of public financial results before we own a business, so we are unlikely to ever invest in an IPO.
Fee-only financial planning and investing
Your RSUs, options and ESPP can fund the life you want: financial independence on your timeline, a home, your kids’ education, the freedom to change course. We build the plan around those goals, make the tax decisions your equity creates, and invest for the long term in a focused portfolio of businesses we understand.
 Led by founder Jim Spinosa, a long-term value investor and former product leader at Amazon and CVS Health.
Example: why RSU withholding often falls short
Shortfallowed with your return or estimated payments
$52,000
About
Founder, Chief Investment Officer and Chief Compliance Officer
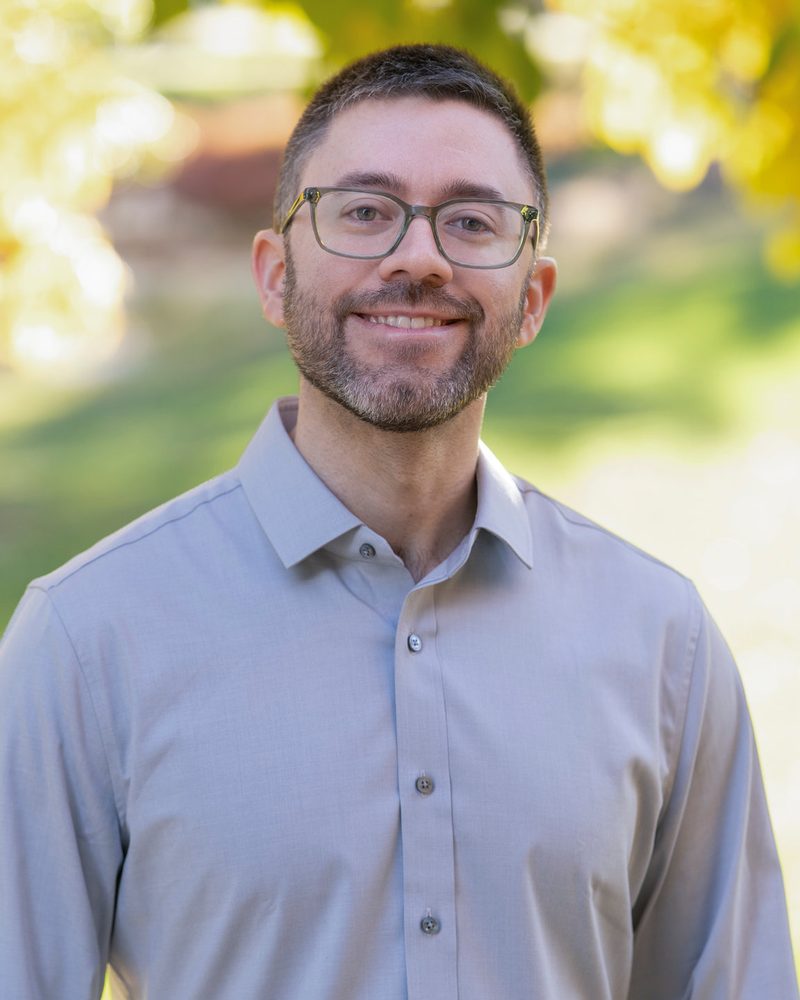
I started watching CNBC and bought my first bank stock in elementary school, and by middle school I was introducing myself to new classmates as a future “stock broker” (when that profession still existed).
I am a value investor. I look for a small number of excellent businesses, buy them when the price is sensible, and own them for years, staying away from what I don’t understand. In most years I read 30 to 40 books, mostly about business and finance, and investing is the work I love most. That approach is what led me to start Inference Wealth.
Before founding the firm, I spent more than 13 years in technology product management. Most recently I was an Executive Director at Oak Street Health, part of CVS Health, where I led a product organization of more than 20 people. Before that I spent six years at Amazon as a Principal Product Manager–Technical in search, where I led the migration from a legacy search engine to the search engine Amazon.com currently uses.
My own pay has included long-term incentive plan (LTIP) awards and an employee stock purchase plan (ESPP) at CVS Health, RSUs at Amazon, and ISOs and non-qualified stock options at earlier companies such as Glassdoor. Each came with decisions: when to sell, what to hold, how much to set aside for taxes, and how it all fit with what my family wanted. Inference Wealth is built to make those decisions with you, around your goals, and to invest the proceeds in a way that fits your timeline and risk tolerance.
You work with me directly, from the first call through every review. Book an intro call to start the conversation.
How we invest
The Inference Wealth equity model is the center of how we invest. It is included in Wealth Management, sized to each client’s goals and risk tolerance, and available on its own through Investment Management.
We want a record of public financial results before we own a business, so we are unlikely to ever invest in an IPO.
We would rather own good businesses through a downturn than trade around it. Low turnover also keeps gains long-term.
Your paycheck and unvested equity are already a large position in one company. We size your allocation to the model with that exposure in view.
How much you hold in the model, and what sits alongside it, follows from when you need the money and what it is for.
The equity model is concentrated. It can be more volatile than the broad market, may underperform its benchmark for multi-year periods, and may be concentrated in technology, the same sector many clients work in. Valuation estimates can be wrong. All investing involves risk, including loss of principal. See Item 8 of our Form ADV Part 2A for the full list of risks.
Who we help
You are busy doing your job well, and your compensation has outgrown the time you have to manage it. We start with what you want your money to do, then work back to the decisions in front of you.
Retire early, take a sabbatical, or leave to start something. We model when the numbers work, what has to stay true, and which decisions move the date.
Decide what to keep and what to sell on a schedule tied to your goals and your tax brackets, so one company’s stock price doesn’t decide your future.
A projection updated as you vest, exercise and sell, with estimated payments planned ahead, so a large balance due doesn’t catch you off guard.
A home purchase, college savings, insurance and estate documents belong in the same plan as your equity, because they draw on the same money.
If you think AI could shorten your career, we model that scenario next to your base plan: fewer peak-earning years, a bridge period of lower income, and the savings, diversification and tax moves that would still reach your goals. These are scenarios, not predictions.
Compensation we plan around
Services
Wealth Management is the full relationship: a plan built around your goals, tax planning for your equity, and a portfolio managed to fit both. Investment Management invests an amount you choose in the Inference Wealth equity model, with no financial planning.
One ongoing relationship covering your goals, the tax decisions your equity creates, and your whole portfolio.
Discretionary management of the amount you choose to invest in the Inference Wealth equity model. It does not include financial planning or management of your other assets.
Equity-only and concentrated: expect more volatility than the broad market and possible multi-year periods of underperformance.
Tax planning, included in Wealth Management
Every vest, purchase and exercise comes with a tax date. We plan ahead of those dates so the decisions serve your goals, instead of explaining the bill in April. These are strategies we evaluate for clients. Each has trade-offs, and we’ll tell you which apply to you.
At each vest and purchase
RSU vests, ESPP purchases
We project your full-year tax and schedule estimated payments or extra withholding, so the balance due is planned and penalties are avoided where safe harbors allow.
Trade-off: Safe harbors avoid penalties, not the tax itself.
We compare selling at purchase with holding long enough for a qualifying disposition, which changes how part of the gain is taxed.
Trade-off: Holding adds exposure to your employer’s stock.
A vest or ESPP purchase within 30 days of selling company stock at a loss can disallow the loss. We time sales around your schedule.
Trade-off: We need to know about every account that buys the same stock.
Throughout the year
Accounts and savings
Above the Roth income limits, IRA conversions and after-tax 401(k) contributions can still add Roth savings every year.
Trade-off: Pre-tax IRA balances and your 401(k) plan’s rules can limit this.
Holding tax-inefficient investments in retirement accounts and tax-efficient ones in taxable accounts can raise after-tax returns.
Trade-off: The benefit varies with your rates and account sizes, and can be small.
You own an index as individual stocks instead of a fund. Losses on single positions are harvested automatically throughout the year to offset gains, and your employer and its sector can be excluded.
Trade-off: Harvesting defers tax rather than eliminating it, and builds low-basis positions that are costly to sell later.
Before December 31
Decisions tied to the tax year
We estimate how much you can exercise each year before the alternative minimum tax applies, and spread exercises across years.
Trade-off: If the stock falls after exercise, you can owe AMT on value you no longer have.
Donating long-held stock avoids tax on the gain, and grouping gifts into a high-income year through a donor-advised fund can make itemizing worthwhile.
Trade-off: Gifts to a donor-advised fund are irrevocable, and deduction limits apply.
Around a liquidity event
IPO, acquisition, tender offer
We plan sales of concentrated stock over several tax years, choose specific lots, and pair gains with harvested losses where possible.
Trade-off: You stay exposed to the stock while sales are spread out.
Section 1202 can exclude gain on qualifying small business stock. We track acquisition dates and holding periods and bring your tax advisor in early.
Trade-off: Eligibility is determined by your tax professional, not by us.
We build sale plans that fit your employer’s trading windows, lockups and any Rule 10b5-1 plan you adopt.
Trade-off: You are responsible for telling us about employer restrictions.
Tax planning is part of our financial planning service. Inference Wealth does not prepare tax returns or provide legal advice. Consult a qualified tax professional before acting on any strategy; with your permission we work directly with your CPA or attorney.
Have a vest, exercise or sale coming up? Book an intro call and we’ll talk through what it means for your goals.
Book an intro callHow it works
Tell us what you want your money to do and what’s on your mind. No cost and no obligation. Book an intro call
We gather your grants, pay stubs, tax returns and statements. You receive our Form ADV brochure before signing anything.
You receive a written plan built around your goals. We open accounts at Altruist and move assets in on a tax-aware schedule.
Quarterly reviews, an annual planning meeting, and planning around the vests, exercises and deadlines that matter to your plan.
Pricing
Planning for a household with RSUs, options and a tax bill to manage takes similar work at $400,000 as at $800,000, so Wealth Management is a flat $7,200 a year up to $850,000. Above that, each tier’s rate applies only to the assets within that tier, like tax brackets, so your effective rate declines as assets grow.
Financial planning, tax planning and investment management
| Assets under management | Annual fee |
|---|---|
| First $0 – $850,000 | $7,200 flat |
| Next $850,001 – $3,000,000 | 0.85% |
| Next $3,000,001 – $6,000,000 | 0.75% |
| Next $6,000,001 – $10,000,000 | 0.65% |
| Above $10,000,000 | 0.50% |
The Inference Wealth equity model, without financial planning
| Assets under management | Annual fee |
|---|---|
| First $0 – $3,000,000 | 0.65% |
| Next $3,000,001 – $6,000,000 | 0.55% |
| Next $6,000,001 – $10,000,000 | 0.45% |
| Above $10,000,000 | 0.40% |
FAQ
Inference Wealth is a fee-only fiduciary. We have a fiduciary duty to act in your best interest throughout our relationship, and we are paid only by clients, through the published fees above. We do not receive commissions or payments from fund companies, insurers or other product providers, and we do not pay anyone to refer clients.
We talk about what you want your money to do, how you are paid, and what is on your mind. You don’t need to prepare anything, though a recent pay stub and a grant or vesting summary help. If it looks like a fit, I’ll explain how we would work together and what it would cost. If not, I’ll tell you.
No. Inference Wealth is based in Colorado, and we expect most of our clients to live in other states. Meetings happen by video.
We can work with clients in every state except Louisiana, which requires an adviser to register there before taking on a single client. In Texas, we file a notice with the state before working with you. In any state, once we serve more than five clients there, we register in that state.
Accounts are held in your name at Altruist Financial LLC, an unaffiliated SEC-registered broker-dealer and member of FINRA and SIPC. You receive statements and trade confirmations directly from Altruist. We can trade and, with your written authorization, deduct our fee, but we cannot withdraw your money.
No. We do tax planning: projecting your liability, timing sales, exercises and contributions, and recommending strategies. A CPA prepares your return and an attorney drafts estate documents. With your permission we work with both directly, and we can recommend professionals if you need them.
Wealth Management has a $300,000 minimum in managed assets, which we may reduce or waive case by case. Because the first $850,000 carries a flat $7,200 annual fee, smaller accounts pay a higher percentage of assets.
Yes. Concentrated positions are a core part of the work. Your employer’s insider trading policy, blackout periods, lockups and any Rule 10b5-1 plan still govern when shares can be sold. We do not have access to those policies or to any insider information, so you are responsible for telling us about restrictions and for confirming that sales comply with them.
If you want tax returns prepared, a CPA is the right first call; we plan and coordinate with them. If your investable assets are well under $300,000 and you are paid salary only, our flat fee would be a high percentage of your assets. And if you are looking for short-term trading or market timing, we are not the right firm.
Give 30 days’ written notice. You pay the prorated fee through the termination date; because we bill in arrears, nothing is prepaid. If you did not receive our Form ADV brochure at least 48 hours before signing, you can cancel within five business days of signing at no cost.
Ending the advisory relationship does not end the tax consequences of how your portfolio was built. Positions with large unrealized gains, including those that accumulate through direct indexing and tax-loss harvesting, can be costly to sell. They can generally be transferred to another custodian in kind instead, but a new adviser may still want to reposition them.
Get started
Book a 30-minute intro call. Tell us what you want your money to do and what decisions are coming up, and we’ll talk through your situation and whether working together makes sense. There is no cost and no obligation.
Book an intro callOnline scheduling opens soon. Until then, call to set up a time.